Real situations. Better questions. Smarter decisions.
Tax and business decisions rarely come down to a single number.
The right question at the right time can uncover a better tax outcome, identify a risk, improve cash flow or change the way a business decision is approached.
Explore real-world examples of how we have helped clients look beyond the obvious and make more informed financial decisions.
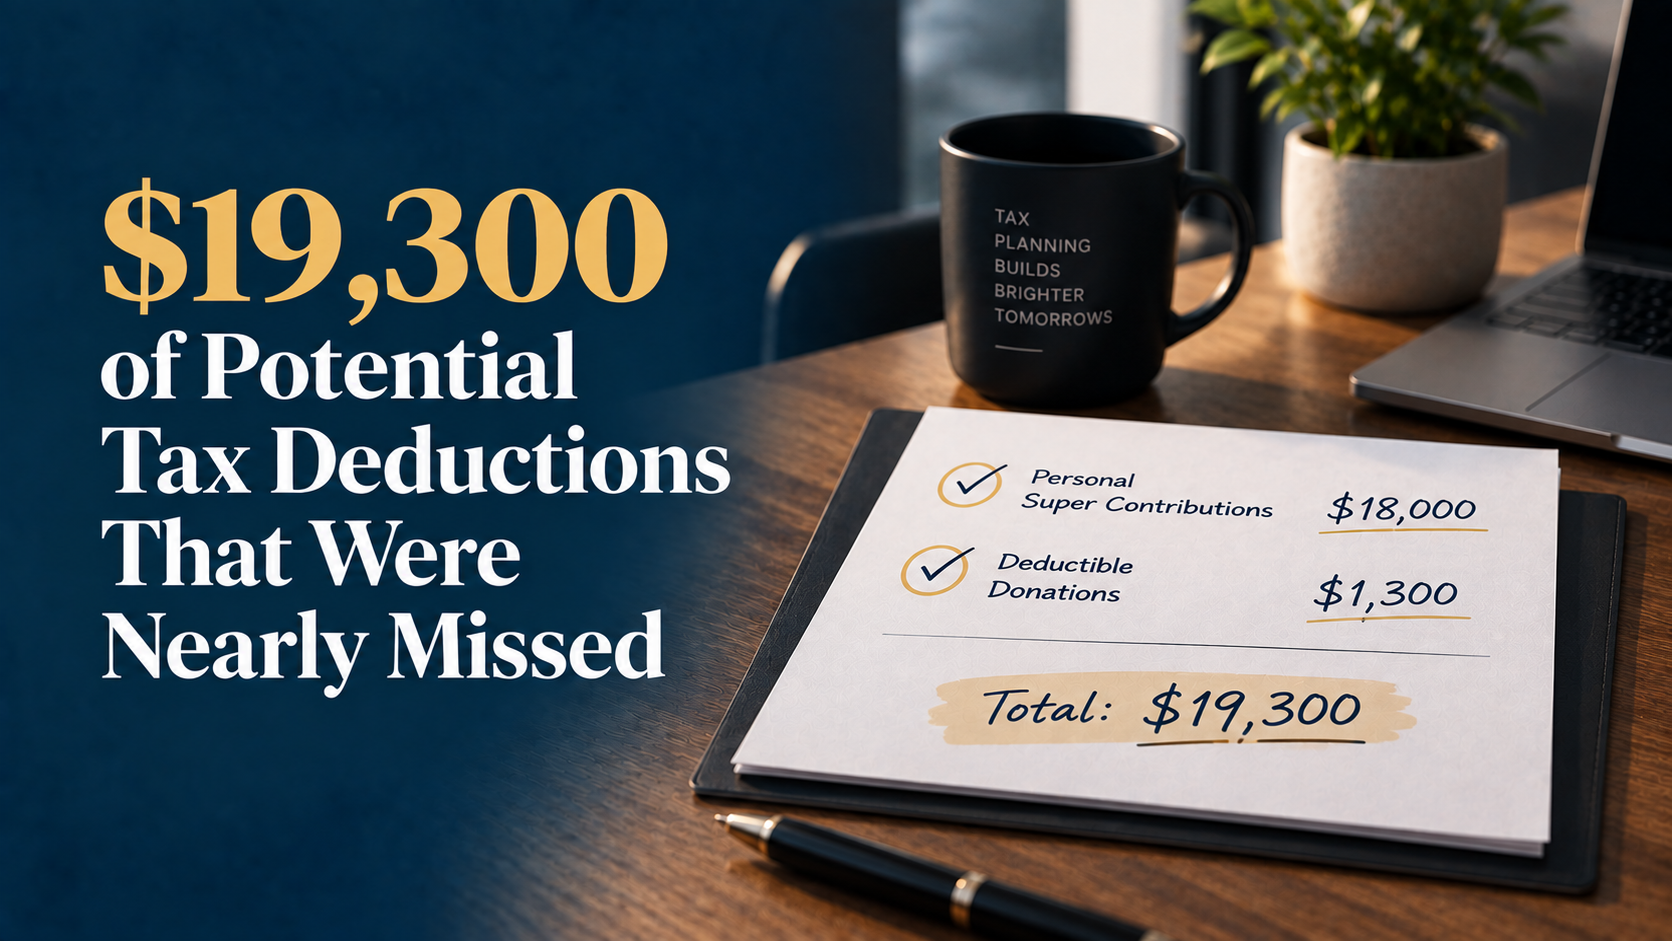
$19,300 of Potential Tax Deductions That Were Nearly Missed
A client came to us for a second opinion on their taxreturn.
Sometimes, a second opinion can identify items that warrant acloser look.
After thoroughly reviewing their position, we identified thattheir draft tax return had not included approximately:
- $18,000 in personal superannuation contributions, and
- $1,300 in deductible donations
That's $19,300 of potential deductions thatrequired further consideration.
What makes this particularly important is that tax agentsgenerally have access to a significant amount of pre-fill information,including information relating to contributions made to regulatedsuperannuation funds.
But having access to the information is not the same as actuallyreviewing it properly.
We have seen situations where information is available throughpre-fill reports but is overlooked, not followed up, or simply not discussedwith the client.
Clients themselves may not realise that eligible personalsuperannuation contributions can potentially be claimed as a tax deduction,subject to the relevant requirements — including lodging a valid notice ofintent to claim a deduction with their super fund.
So if the accountant doesn't identify it and the client doesn'tknow to ask about it, a significant potential deduction can easily be missed.
The information was there —the review mattered
The information can be sitting there in front of you and still bemissed.
Preparing a tax return properly means reviewing the informationavailable, understanding what the client has actually done during the year, andfollowing up when something warrants further investigation.
In this case, that review identified $19,300of potential deductions thatmay otherwise have been overlooked.
Having the information is one thing. Knowing what to look for —and actually reviewing it — is another.
Generalinformation only. Deductibility of personal superannuation contributionsdepends on the applicable requirements, including a valid notice of intentbeing lodged with and acknowledged by the superannuation fund within therequired timeframe. Contribution caps and excess contribution rules should alsobe considered. Donation deductions depend on the recipient, nature of thepayment and applicable tax rules.
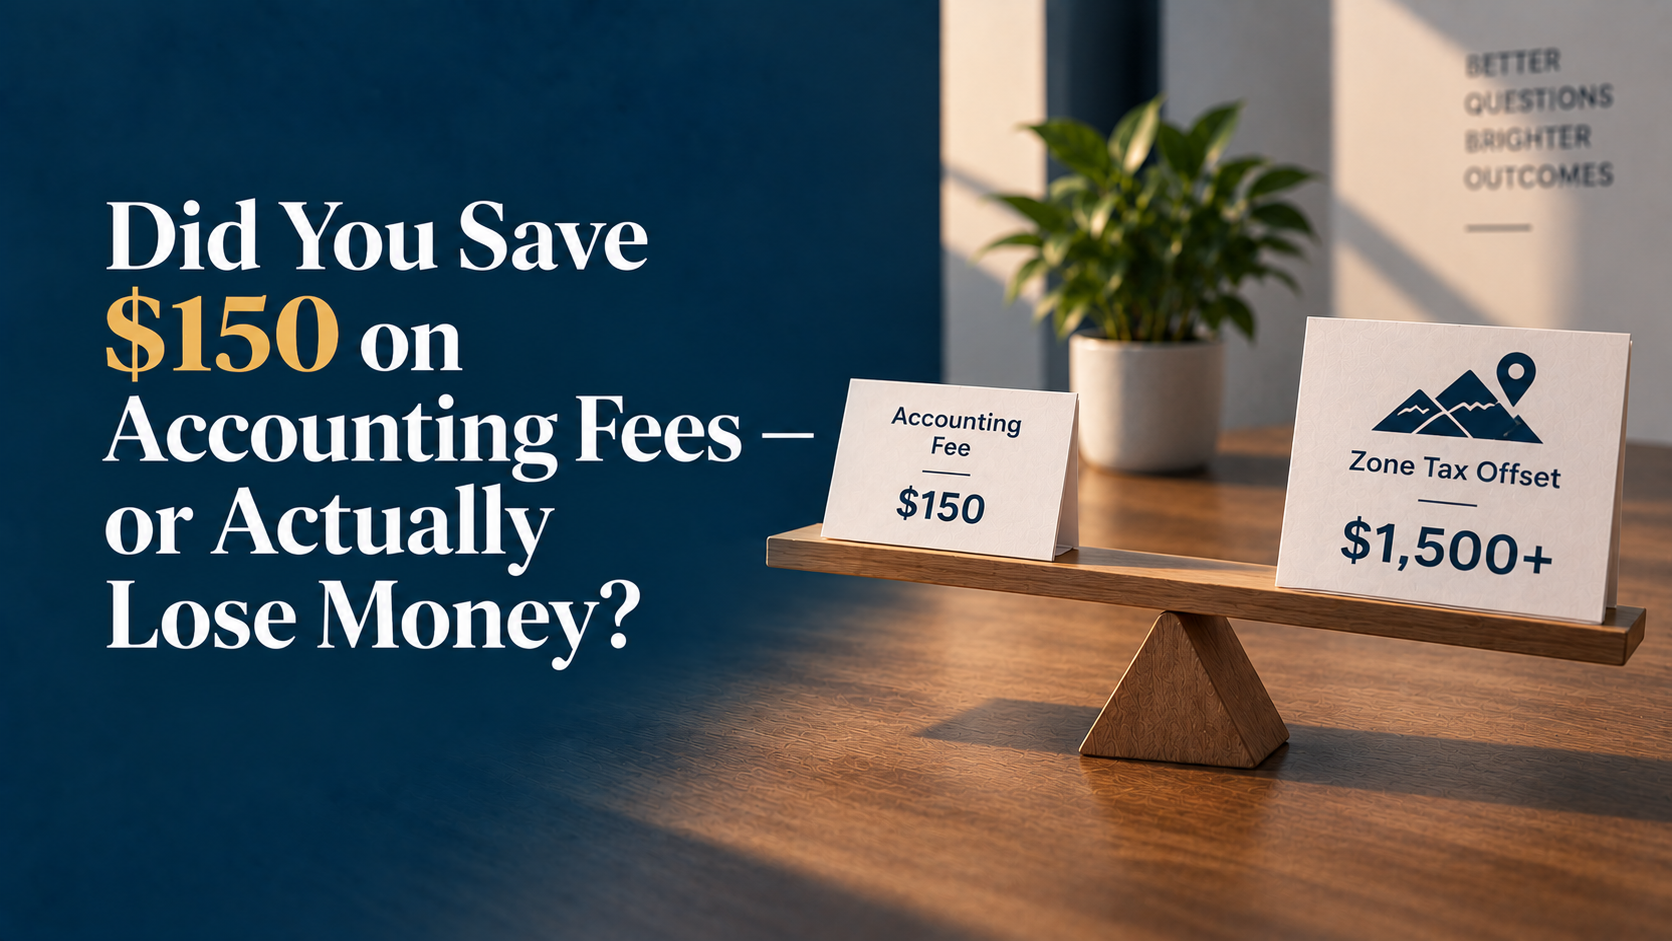
Did You Save $150 on Accounting Fees — or Actually Lose Money?
It's natural to compare accounting fees.
If one accountant charges $150 less to prepare a tax return, thecheaper option can appear to be an obvious saving.
But the accounting fee is only one number.
We have seen new clients who had been living in eligible regionalareas but had not been claiming the Zone Tax Offset, despitepotentially being entitled to it.
The returns may otherwise have been prepared correctly.
The issue was simply that an entitlement hadn't been identifiedand considered.
A cheaper fee doesn't necessarily mean a cheaper overall outcome
The Zone Tax Offset is available to eligible taxpayers whose usualplace of residence is in specified remote areas of Australia, subject to therelevant requirements.
The amount isn't the same for everyone. It can depend on theparticular zone and, in some circumstances, eligible dependants and otherfactors.
For an eligible taxpayer, the offset can therefore be worthconsiderably more than a relatively small difference between two accountants'fees.
And that's only one item on one tax return.
The same principle can apply to depreciation, superannuationcontributions, deductible expenses, CGT, business structures and tax-planningopportunities.
That doesn't mean the more expensive accountant is automaticallybetter.
Price alone simply doesn't tell you the value of the work beingperformed.
What are you actually paying for?
When comparing accountants, the question shouldn't only be:
“How much will you charge me?”
It should also be:
“What are you actually reviewing for that fee?”
A lower fee can represent excellent value where the appropriatework is being performed.
A higher fee can represent poor value if it isn't.
What matters is whether the accountant understands the client'scircumstances, identifies the issues that warrant investigation and considersthe concessions, deductions and planning opportunities that may legitimately beavailable.
For the clients we reviewed, the Zone Tax Offset was a relativelysimple example of something that could easily be overlooked if nobody asked theright questions about where they lived and whether they qualified.
The difference in accounting fees may have been relatively small.
The difference in the quality and scope of the review can be muchlarger.
This case study has been generalised and certain details have beenchanged to protect client and business confidentiality. General informationonly. Eligibility for the Zone Tax Offset depends on the taxpayer'scircumstances, including their usual place of residence, the relevant zone, therequired period of residence and, where applicable, dependant and othereligibility rules. The amount of the offset varies according to the taxpayer'scircumstances.
Five Years of Outstanding Tax Returns — But the Client Was Actually Due a Refund
Having five years of outstanding tax returns can feeloverwhelming. The longer they remain outstanding, the easier it can become tokeep putting them off.
We recently assisted a client who had five years of taxreturns outstanding. They finally decided it was time to get everythingback up to date and, after working through the outstanding years, there was aresult they weren't necessarily expecting: they were actually entitledto a tax refund.
Being behind doesn'tautomatically mean you owe tax
People can sometimes assume that if they haven't lodged taxreturns for several years, there must be a significant tax bill waiting forthem. That's not necessarily the case.
The outcome depends on what actually happened during those years,including income earned, tax withheld, deductions available and the client'sbroader circumstances. For this client, once we obtained the relevantinformation and prepared the outstanding returns, the overall position resultedin a refund rather than additional tax payable.
The hardest part can begetting started
When tax returns have been outstanding for several years, peoplecan become reluctant to contact an accountant. They may be wondering howmuch they will owe, whether there will be penalties, and where they should evenstart.
But delaying the issue doesn't provide the answer. Reviewing theposition does.
We worked through each of the outstanding years, identified theinformation required and brought the client's tax affairs back up to date.Instead of discovering the large tax liability they may have feared, the clientended up with a refund.
Don't assume the outcome
Whether you are one year behind or several years behind, the firststep is to establish your actual position. You may have tax to pay, you may beentitled to refunds, or there may be outstanding lodgment obligations that needto be addressed. You won't know until the numbers are reviewed.
For this client, five years of outstanding tax returnsended with money coming back to them rather than another bill to pay.
Sometimes the situationyou've been putting off isn't as bad as you think. The important thing is toget started.
General information only.Tax outcomes depend on individual circumstances. Outstanding returns may besubject to ATO compliance action, penalties and interest where applicable, andrefunds may be applied against existing tax or other government debts.
The Business Was Finished — But Extracting the Profits Immediately Could Have Cost Around $126,000 in Tax
The husband and wife had retired, their business had finished, andthey wanted to close their company and move on.
That seemed like the logical next step.
But before extracting the remaining money and closing the company,we looked at what was still sitting inside it.
The company had approximately $800,000 in retained earnings,together with sufficient franking credits accumulated from company tax paidover the years.
Rather than simply taking everything out immediately, we comparedtwo different strategies:
Extract the accumulated profits now — or progressively distributethem during retirement?
Under our modelling, the difference between those two approacheswas approximately $196,000.
Retirement changed the equation
While the husband and wife were working, they had higher levels ofpersonal taxable income.
Now they were retired and expected their taxable incomes to besubstantially lower.
That mattered because eligible Australian-resident shareholdersreceiving fully franked dividends generally include both the dividend andassociated franking credit in their assessable income, while receiving acorresponding tax offset for the franking credit.
Where eligible individuals have excess franking credits aftertheir tax liability is calculated, those excess credits may be refundable.
So instead of looking only at the company's $800,000 ofaccumulated profits, we modelled the company and shareholders together.
Approximately $126,000 of tax versus approximately $70,000 ofrefunds
Under our modelling, extracting approximately $800,000 ofaccumulated profits in one financial year could result in approximately $126,000of combined net personal tax forthe husband and wife.
We then modelled an alternative.
Rather than extracting everything immediately, the company couldpotentially remain in place for approximately five years while fully frankeddividends were progressively paid to the shareholders during retirement.
Assuming the husband and wife had no other taxable income, our projectionsindicated that this approach could potentially produce approximately $14,000in combined ATO refunds each year, or around $70,000over five years.
The projected difference between the two strategies was thereforeapproximately:
$196,000.
This wasn't about finding another deduction or somehow avoidingthe company tax that had already been paid.
It was about when the accumulated profits reached theshareholders and how the available franking credits could potentially beutilised during lower-income retirement years.
Closing the business and closing the company are differentdecisions
Once a business stops operating, it's natural to want to cleaneverything up: take out the remaining money, close the bank accounts andderegister the company.
But where a company has substantial accumulated profits andfranking credits, those steps shouldn't automatically happen together.
For these clients, we considered a plannedfive-year exit, progressively distributing accumulated profitsduring retirement and reviewing the position each year as their circumstanceschanged.
Once the accumulated profits had been substantially extracted, thecompany could then be considered for closure after reviewing its remainingassets, liabilities, franking account and other tax consequences.
The business may have been finished.
The tax planning wasn't.
Before closing a company with substantial retained profits, thebetter question may not be:
“How quickly can we close it?”
It may be:
“What's the most tax-effective way to extract the accumulatedprofits first?”
For these clients, modelling that question produced a potentialdifference of approximately $196,000 between the two strategiesconsidered.
This case study has been generalised and certaindetails have been changed to protect client and business confidentiality.General information only. Figures are illustrative and based on the assumptionsused in this case study, including approximately $800,000 of retained profits,sufficient franking credits, eligible Australian-resident individualshareholders and no other taxable income during the projected five-yeardistribution period. Actual outcomes depend on the company's distributableprofits and franking account, shareholder circumstances, other income, Medicarelevy and applicable tax and integrity rules. Liquidation and company wind-updistributions can have different tax consequences and should be specificallyreviewed before a company is wound up or deregistered.
The $2 Million Farm Decision: Sell, Lease or Retire?
A farmer came to us at an important stage in their life.
Their children weren't interested in taking over the farmingbusiness, the farmer was ready to step away, and the farming land was worthapproximately $2 million.
Their initial plan seemed straightforward:
Stop farming, keep the property and lease it to another farmer forretirement income.
There was nothing inherently wrong with that strategy.
But before a $2 million business asset was converted into along-term investment property, we wanted to compare the alternatives.
The farm wasn't just a $2 million property
The land had been actively used in the client's farming business.
That history mattered because eligible small business owners maypotentially access the small business CGT concessions when disposing of qualifying activebusiness assets.
The property had been owned for less than 15 years, so the periodfor which the land had been an active asset relative to the relevant ownershipand test period was particularly important.
Leasing the farm to another farmer wouldn't automatically mean itsprevious active-asset history disappeared.
But changing from personally farming the land to holding it as along-term rental asset could affect the position over time, depending on thecircumstances and when a future sale occurred.
So before the farmer changed how the property was being used, wereviewed the potential CGT position and compared two fundamentally differentretirement strategies:
Keep the farm and live from the rental income — or sell the farmas part of the client's exit from farming and redeploy the capital elsewhere?
A favourable tax outcome made selling worth considering
Our analysis indicated that, subject to satisfying the relevanteligibility requirements, the small business CGT concessions could potentiallyproduce a very favourable outcome if the property was sold.
For example, if a sale at approximately $2million producedan $800,000 capital gain after taking the cost base andrelevant adjustments into account, the available CGT concessions couldpotentially substantially reduce — and depending on the client's circumstances,potentially eliminate — the taxable capital gain.
That didn't automatically mean the farm shouldbe sold.
It meant selling deserved to be properlycompared with leasing rather than being dismissed because the client neededretirement income.
The decision was bigger than CGT
The farmer's real objective wasn't simply to minimise tax.
They needed to turn a lifetime of farming into a sustainableretirement.
Keeping the farm could provide rental income, but it would alsoleave a substantial proportion of the client's wealth concentrated in oneproperty, in one location and one predominant source of retirement income.
Selling could potentially release approximately $2million of capital.
That raised another question:
Could that capital be diversified to provide retirement incomefrom several different sources rather than relying predominantly on one farm?
We worked alongside the client's licensed financial adviser toexplore that broader retirement strategy.
The client considered diversifying the available capital acrossdifferent assets, potentially including residential investment property and adiversified managed investment portfolio, rather than retainingmost of their retirement wealth in a single farming property.
Our role was to analyse the tax consequences of selling versusretaining the farm and the tax implications of the alternatives beingconsidered. The licensed financial adviser separately advised on investmentselection, asset allocation, diversification and the client's broaderretirement strategy.
Diversification doesn't eliminate investment risk. But it gave theclient another option: instead of relying predominantly on one farm for bothretirement income and capital, they could consider having multipleassets, multiple potential income sources and greater flexibility over howtheir capital was held.
Retirement planning started before the farm stopped operating
The client's original plan wasn't necessarily wrong.
Leasing the farm could still have been a legitimate option.
The problem would have been making that decision withoutfirst understanding the alternatives.
For a client approaching retirement with approximately $2 milliontied up in a major business asset, the conversation needed to happen before theasset's use changed — not years later when the client eventually decided tosell.
In this case, the tax analysis opened up a much broader retirementconversation:
Should the client continue relying on one $2 million farmingproperty — or use the opportunity to transition both the business and theirwealth into the next stage of their life?
This case study has beengeneralised and certain details, including financial amounts, have been changedto protect client and business confidentiality. General information only.Eligibility for the small business CGT concessions depends on the taxpayer'sparticular circumstances and the detailed requirements of Division 152,including the basic conditions and active asset test. Ceasing a business orsubsequently leasing an asset does not automatically result in the concessionsbeing unavailable, and the relevant ownership, business-use and timing historymust be considered. Our role was to provide tax analysis of the alternatives.Investment, diversification, asset-allocation and retirement-incomerecommendations should be provided by an appropriately licensed financialadviser.
Asset Protection Gone Wrong: When the Family Home and Business End Up in the Same Trust
Asset protection is important. But simply putting everything intoa trust doesn't necessarily mean your assets are properly protected.
In some circumstances, it can create the opposite result.
We had a client who wanted asset protection and had previouslypurchased their principal place of residence — theirfamily home — in the same trust used to operate their business.
When we reviewed the structure, we immediately asked:
Why was the family home sitting in the same structure carrying onthe business?
That question exposed several issues.
What was the home actually being protected from?
People sometimes consider trust ownership because they'reconcerned about protecting assets from future risks, including businesscreditors or a possible relationship breakdown.
But putting a family home into a discretionary trust doesn'tautomatically put it beyond the reach of family-law proceedings.
The treatment of trust assets in family-law matters dependsheavily on the circumstances, including who controls the trust, how it has beenoperated, the parties' interests and contributions, and the terms of the trustitself.
So if relationship risk is the concern, “putthe house in a trust” isn't a complete asset-protection strategy.Specialist family-law advice is required, and other strategies — potentiallyincluding a properly prepared Binding Financial Agreement where appropriate —may need to be considered with a family lawyer.
The starting question should always be:
What exactly are you trying to protect the property from?
Business creditors? Professional liability? Personal guarantees?Bankruptcy? Relationship breakdown? Estate-planning risks?
Different risks can require very different solutions.
The tax cost of putting the family home in a trust
There can also be a significant tax trade-off.
Where an eligible individual owns and occupies a property as theirmain residence, the main residence CGT exemption can potentially eliminate thecapital gain when the property is eventually sold.
An ordinary discretionary trust generally doesn't receive thatsame exemption simply because a beneficiary and their family live in theproperty.
Consider a simple example.
A family home is purchased for $800,000 and, years later, is worth $1.5million.
That's a $700,000 increase in value before considering the property'sactual CGT cost base and other adjustments.
If an eligible individual had owned and occupied the property astheir main residence throughout the relevant period, the main residenceexemption could potentially eliminate the resulting capital gain.
But where an ordinary discretionary trust owns the property, thesame outcome generally isn't available merely because a beneficiary has livedthere as their family home.
There can also be land-tax consequences.Depending on the State or Territory, trust ownership may prevent access to anordinary principal-residence land-tax exemption or result in different land-taxtreatment.
So the client may potentially give up valuable tax concessions inpursuit of asset protection that doesn't necessarily provide the protectionthey thought it would.
The bigger problem: the business was in the same trust
In this client's case, there was another fundamental issue.
The same trust holding the family home was also carrying on thebusiness.
The client was effectively putting:
the asset they wanted to protect
in the same structure as
the activity creating commercial risk.
That undermined one of the fundamental objectives of assetprotection — separating valuable passive assets from operating risk.
It raised the obvious question:
What exactly are we protecting the home from if the home and thebusiness are sitting together?
That doesn't mean a particular structure automatically protects anasset from every creditor or claim. Personal guarantees, insolvency law, trustarrangements and other circumstances can materially affect the outcome. But itdemonstrates why asset protection needs to be designed around the actual risksrather than simply assuming that “a trust” provides protection.
Fixing the structure later can be expensive
Unfortunately, once a property has already been acquired in thewrong structure, fixing it isn't necessarily as simple as changing the name onthe title.
Transferring real property from a trust to an individual canpotentially trigger CGT, transfer duty, refinancing andlegal costs, together with other tax and commercialconsequences.
That's why these questions should ideally be answered beforethe property contract is entered into.
Who should buy the property? What risks are we protecting against?Where should the business operate? What tax concessions could be lost? What arethe land-tax and duty consequences? And does the proposed structure actuallyachieve the legal protection the client expects?
For this client, the family home and operating business had endedup in the same trust. That potentially meant losing access to the ordinary mainresidence CGT exemption while also failing to properly separate the home fromthe risks associated with the business.
Asset protection isn't simply about putting assets into a trust.It's about putting the right assets in the right structures for the rightreasons.
Sometimes the most valuable structuring question needs to be askedbefore anything is purchased:
Who should actually own it?
This case study has been generalised and certain details have beenchanged to protect client and business confidentiality. General informationonly. Trust, asset-protection, family-law, bankruptcy, CGT, transfer-duty andland-tax outcomes depend on the circumstances and applicable jurisdiction.Trust ownership does not automatically protect assets from creditors orfamily-law claims. Specialistlegal advice should be obtained on asset-protection and family-law matters. Taxconsequences should be considered before acquiring or transferring property.
$300,000 Sitting in a Company Bank AccountWhile the Directors Had a Mortgage
One of our clients had accumulated more than $300,000in cash inside their company.
Much of it was sitting in a company savings account.
At the same time, the directors personally had a home mortgage onwhich they were paying non-deductible interest.
But when we reviewed the company's balance sheet, something elsestood out:
The company actually owed money to the directors.
That changed how we looked at the $300,000.
Before extracting profits, we looked at what the company alreadyowed them
Over time, the directors had contributed or advanced money to thecompany, creating genuine amounts owing back to them.
That's an important distinction.
If a director owes money to the company, Division7A and other tax consequences may need to be considered.
But where the company genuinely owes money to thedirector, repayment of that loan principal will generally notcreate additional assessable income for the director merely because the debt isrepaid.
So before considering dividends or other ways of extractingaccumulated company profits, we reconciled the director loan accounts anddetermined how much of the company's cash represented money that could simplybe repaid to the directors.
A substantial amount could be returned on that basis.
For any additional extraction of accumulated company profits, weseparately considered matters such as available franking credits, theshareholders' tax position and Division 7A rather than simply treating thecompany's bank balance as personal money.
Then we compared the company cash with the private mortgage
Suppose $200,000 could legitimately be returned to thedirectors and effectively applied against a private home mortgage chargingapproximately 6%.
That could potentially reduce mortgage interest by around:
$12,000 per year.
That's not a $12,000 tax deduction.
It's potentially $12,000 of interest the directors nolonger have to pay.
Meanwhile, leaving surplus cash inside a company savings accountcould mean the company continues earning taxable interest while the directorscontinue paying non-deductible mortgage interest personally.
Looking at those two positions separately could therefore miss anopportunity sitting directly on the balance sheet.
But we weren't going to empty the company bank account
The fact that a company has $300,000 in cash doesn't mean $300,000is surplus.
Before returning money to the directors, we also considered thecompany's requirements for tax, GST and PAYG obligations, employee costs andsuperannuation, suppliers, operating expenses, planned purchases and anappropriate working-capital reserve.
Only genuinely surplus cash should be considered.
We also considered how any returned funds would be applied againstthe home loan. Offset and redraw arrangements can produce different outcomes,particularly if the property later becomes income-producing, so the appropriatelending structure needs to be considered separately.
The opportunity was sitting on the balance sheet
The strategy didn't start with finding another tax deduction.
It started by asking:
Why does the company have more than $300,000 sitting in cash?
How much does it genuinely need?
Does it already owe some of that money back to the directors?
For these clients, answering those questions identified asubstantial amount that could potentially be returned to them and put to moreproductive use — including reducing thousands of dollars of non-deductiblehome-loan interest each year.
Sometimes the balance sheet tells you more than the tax return.
This case study has been generalised and certain details have beenchanged to protect client and business confidentiality. General informationonly. Director loan balances must represent genuine liabilities and should bereconciled and verified before repayment. Dividend, franking and Division 7Aconsequences depend on the particular circumstances. Companies should retainappropriate working capital and meet their liabilities as they fall due. Ourrole was to advise on the taxation consequences of extracting and applying thefunds. Financial product advice may require an appropriately licensed financialadviser, while offset, redraw, lending and credit matters may requireappropriately licensed credit advice.
Don't Wait Until Tax Time for Your Rental Property Refund
A large tax refund can feel like a good result. But sometimes itraises another question: Why did you have to wait until the end of theyear to get your own money back?
We had a client who owned two rental properties thatgenerated significant deductible expenses, reducing the client's overalltaxable income. Each year, however, tax continued to be withheld from theirsalary at the normal rate. They would then lodge their tax return and receive asubstantial refund.
This had been happening for years, so we discussed anotheroption: a PAYG withholding variation.
Getting the benefit duringthe year
Whereappropriate, an employee can apply to the ATO to vary the amount of tax theiremployer withholds from their salary. For someone with negatively geared rentalproperties, this can allow the expected rental property deductions to be takeninto account during the year, rather than waiting until the taxreturn is lodged.
If the ATOapproves the variation, the employer can reduce the PAYG withholding deductedfrom the employee's pay, resulting in more cash in the client's bankaccount throughout the year.
Consider a simpleexample. If a property investor would ordinarily receive a $12,000 taxrefund because of their rental property deductions, they effectivelywait until tax time to receive that money. With an appropriately calculated andapproved variation, some of that benefit could instead be reflectedprogressively in their take-home pay — potentially around $1,000 permonth in additional cash flow.
The overall taxoutcome may ultimately be similar. The difference is when the clientgets access to the cash.
Cash flow has value
Having that cash availablethroughout the year could help with mortgage repayments, rental propertyexpenses, household costs or other financial commitments.
For years, our client hadbeen waiting until their tax return was lodged to receive the benefit ofdeductions they were already expecting to incur. We simply asked whether thatstill made sense.
A large refund can sometimesmean more tax was withheld during the year than was ultimately required basedon the taxpayer's final position. That's why we don't just ask “How bigis your refund?” We also ask “Could we improve your cash flowduring the year?”
Tax planning can also be about timing
For this client, the PAYG withholding variationwasn't necessarily about reducing their ultimate tax liability. It was about whenthey received the benefit of deductions they were already expecting to claim.
Instead of waiting until tax time for a largerefund, an appropriately calculated and approved variation could potentiallyimprove their cash flow throughout the year.
Good tax planning doesn't always change how much tax youultimately pay. Sometimes it changes when you get access to the cash.
General information only. PAYG withholding variationsare subject to ATO requirements and approval. The appropriate variation dependson expected income, deductions and other circumstances. Estimates should bereasonable, as an inappropriate variation can result in insufficient tax beingwithheld and tax payable on assessment.
Buying an Investment Property? We Looked Beyondthe Client's Minimum Salary
Keeping yoursalary relatively low can sometimes make sense when you operate through acompany and don't need all of the business profits personally.
But what happens when you actually need the money?
We had a client operating a successful business through a company.They had historically taken a relatively modest salary and left a significantamount of profit and cash inside the company.
Then their circumstances changed: they wanted to purchasean investment property and needed additional personal cash to help fund it.
Rather than simply continuing with the same salary strategy, wereviewed the client's broader position — including accumulated company profits,available cash, franking credits, Division 7A and the tax consequences ofextracting additional profits.
How should the money comeout of the company?
The first question wasn't simply, “How much money can wetake out?”
It was, “What's the appropriate way to extract it?”
We considered the relative consequences of additional salaryversus franked dividends. Salary may generally be deductible to the company butcan also have PAYG withholding, superannuation and other consequences.Dividends aren't deductible to the company, but where the company hassufficient franking credits, those credits can potentially be attached todividends and recognised in the shareholder's personal tax position.
In this client's circumstances, we considered a planned dividendstrategy, including interim dividends during the financial year whereappropriate, rather than waiting until year-end to decide how much money shouldbe extracted.
That provided the client with additional personal cash that couldbe put towards the proposed investment property purchase.
Working backwards from thecash the client actually needed
Simply declaring a $100,000 dividend doesn't necessarily mean theclient has $100,000 available to spend without further tax consequences.
A fully franked dividend generally comes with a franking creditrepresenting company tax already paid. The cash dividend plus the frankingcredit is generally included in the shareholder's assessable income, with acorresponding franking tax offset. Depending on the client's overall taxableincome and marginal tax rate, additional personal tax may still be payable.
So we worked backwards from the client's objective. How much cashdid they actually need for the property purchase? How much should bedistributed? What franking credits were available? And what additional personaltax could arise?
That gave the client a much clearer understanding of the after-taxcash actually available for the investment, rather than simply looking atthe balance in the company bank account.
Avoiding an unintendedDivision 7A problem
This planning was also important because company money isn'tautomatically the shareholder's personal money.
Simply transferring company cash to a shareholder to fund aprivate investment can potentially create Division 7A consequences if theamount isn't otherwise appropriately dealt with. Depending on thecircumstances, a payment or loan by a private company to a shareholder orassociate can potentially result in an unfranked deemed dividend.
So instead of saying, “The company has the cash — use itfor the deposit,” we considered how the money should legitimately beextracted before it was used.
In this case, properly declared franked dividends allowed us toplan the distribution of accumulated company profits while taking the availablefranking credits into account.
That's very different from withdrawing the money first andworrying about the tax consequences later.
Looking at the property anddividends together
The investment property would also change the client's personaltax position.
Once the property was held for income-producing purposes, eligibleexpenses could potentially include interest on investment borrowings, councilrates, property management fees, insurance, certain repairs and maintenance,capital works deductions and depreciation on eligible depreciating assets.
Where allowable rental deductions exceed rental income, theresulting net rental loss may generally reduce the client's other taxableincome, subject to the normal tax rules.
That was relevant because the planned dividends would increase theclient's assessable income. Rather than considering the dividend strategy andinvestment property in isolation, we modelled how the different componentswould interact in the client's overall tax position.
Importantly, negative gearing wasn't the reason to purchase theproperty. A tax deduction only reduces part of an economic cost, and theinvestment itself still needed to make commercial sense.
Tax planning should respondto what the client is trying to achieve
If we had looked only at the client's salary,we might simply have continued with the existing approach. If we had lookedonly at the company, we might have focused on leaving profits inside it.
But neither approach answered the moreimportant question:
What was the client actuallytrying to achieve?
They wanted to purchase an investment property.
That meant considering salary versus dividends,available franking credits, how much after-tax cash they actually needed,Division 7A before accessing company funds, and the tax consequences of theproposed investment property.
Tax planning shouldn'thappen in isolation from the client's objectives. A strategy that made sensewhen the client didn't need the cash needed to be reconsidered when theircircumstances changed.
This case studyhas been generalised, and certain details have been changed to protect clientand business confidentiality. General information only. Dividend, franking,Division 7A, salary, superannuation and rental-property consequences depend onthe particular circumstances. Our role was to advise on the taxationconsequences of the proposed arrangements. Investment decisions and financialproduct advice may require advice from an appropriately licensed financialadviser, while lending and credit matters may require advice from anappropriately licensed credit adviser.
Stay Ahead with Business & Tax Insights
Receive practical business insights, taxation updates and strategic guidance delivered directly to your inbox. Stay informed about legislative changes, emerging opportunities and practical strategies to help you structure, grow and protect your business.
Recognised professional credentials and technology partnerships that demonstrate our commitment to technical excellence and ongoing professional development.
Don't wait until tax time to ask the important questions.
The Tax Bar Australia provides proactive tax and business advice designed to help you make informed decisions before opportunities are missed or problems arise.