Real situations. Better questions. Smarter decisions.
Tax and business decisions rarely come down to a single number.
The right question at the right time can uncover a better tax outcome, identify a risk, improve cash flow or change the way a business decision is approached.
Explore real-world examples of how we have helped clients look beyond the obvious and make more informed financial decisions.
When a 50/50 Partnership Doesn't Necessarily Mean a 50/50 Profit Split
A husband and wife operated a business together through apartnership.
Historically, the partnership profits had been allocated 50/50.
But when preparing the accounts, we noticed that theircircumstances had changed. One partner was now substantially more involved inoperating the business, while the other's involvement had reduced.
Rather than automatically copying the previous year's 50/50treatment, we raised a different question:
Did their existing profit-sharing arrangement still reflect howthey genuinely intended to operate the partnership?
A partner salary isn't an employee salary
One option we considered was whether their partnership arrangementshould provide for a partner salary to the partner taking on the greaterrole, before the remaining partnership profit was divided between them.
The terminology can be misleading.
A partner generally isn't an employee of their own partnershipsimply because they receive a “salary”. A partner salary is generally notan additional tax deduction thatreduces the partnership's taxable profit.
Instead, it can form part of the agreed mechanism for allocatingthe existing partnership profit between the partners.
For example, suppose the partnership generated $200,000of profit.
A straightforward 50/50 allocation would result in $100,000 beingallocated to each partner.
But if the partners had genuinely agreed that one partner wasentitled to a $60,000 partner salary before the remaining profit wasdivided equally, the allocation could instead be:
Partner 1: $60,000 partner salary + $70,000 share of remainingprofit = $130,000
Partner 2: $70,000
The partnership hasn't created another $60,000 deduction.
It still has $200,000 of profit. What has changed is howthat profit is allocated between the partners under their partnershiparrangement.
The commercial arrangement comes before the tax outcome
This isn't something that should simply be decided after 30 Junebased on which spouse has the lower marginal tax rate.
The starting point is the genuine partnership arrangement.
If the partners' roles or commercial expectations have changed, itmay be appropriate to review how they have agreed to share the profits of thebusiness and whether their partnership agreement still reflects that intention.
Any change should be properly considered, agreed and documented prospectively,rather than retrospectively changing the allocation simply to obtain apreferred tax result.
For these clients, one partner's involvement in the business hadchanged substantially.
That gave us a reason to review the underlying arrangement ratherthan automatically carrying forward the previous year's 50/50 allocation.
Don't let last year's taxreturn make this year's decision
A 50/50 partnership doesn'tnecessarily mean every year's partnership profit must always be allocated50/50.
But neither can the profitsplit simply be changed each year to whichever allocation produces the lowesttax bill.
The question is:
What have the partnersgenuinely agreed, and does the documented arrangement still reflect how theyintend to share the economic results of the business?
For this client, recognising that their circumstances had changedprompted a review of an arrangement that might otherwise have simply beencopied from one tax return to the next.
This case study has been generalised, and certaindetails have been changed to protect client and business confidentiality.General information only. Partnership profit allocations and partner salaryarrangements depend on the partnership agreement, the partners' legal andbeneficial entitlements, the timing and implementation of any changes and theapplicable tax law. A partner salary is generally an allocation or advancementof partnership profits rather than deductible employee remuneration. Changesshould reflect a genuine partnership arrangement and be established anddocumented appropriately rather than retrospectively implemented to obtain apreferred tax outcome.
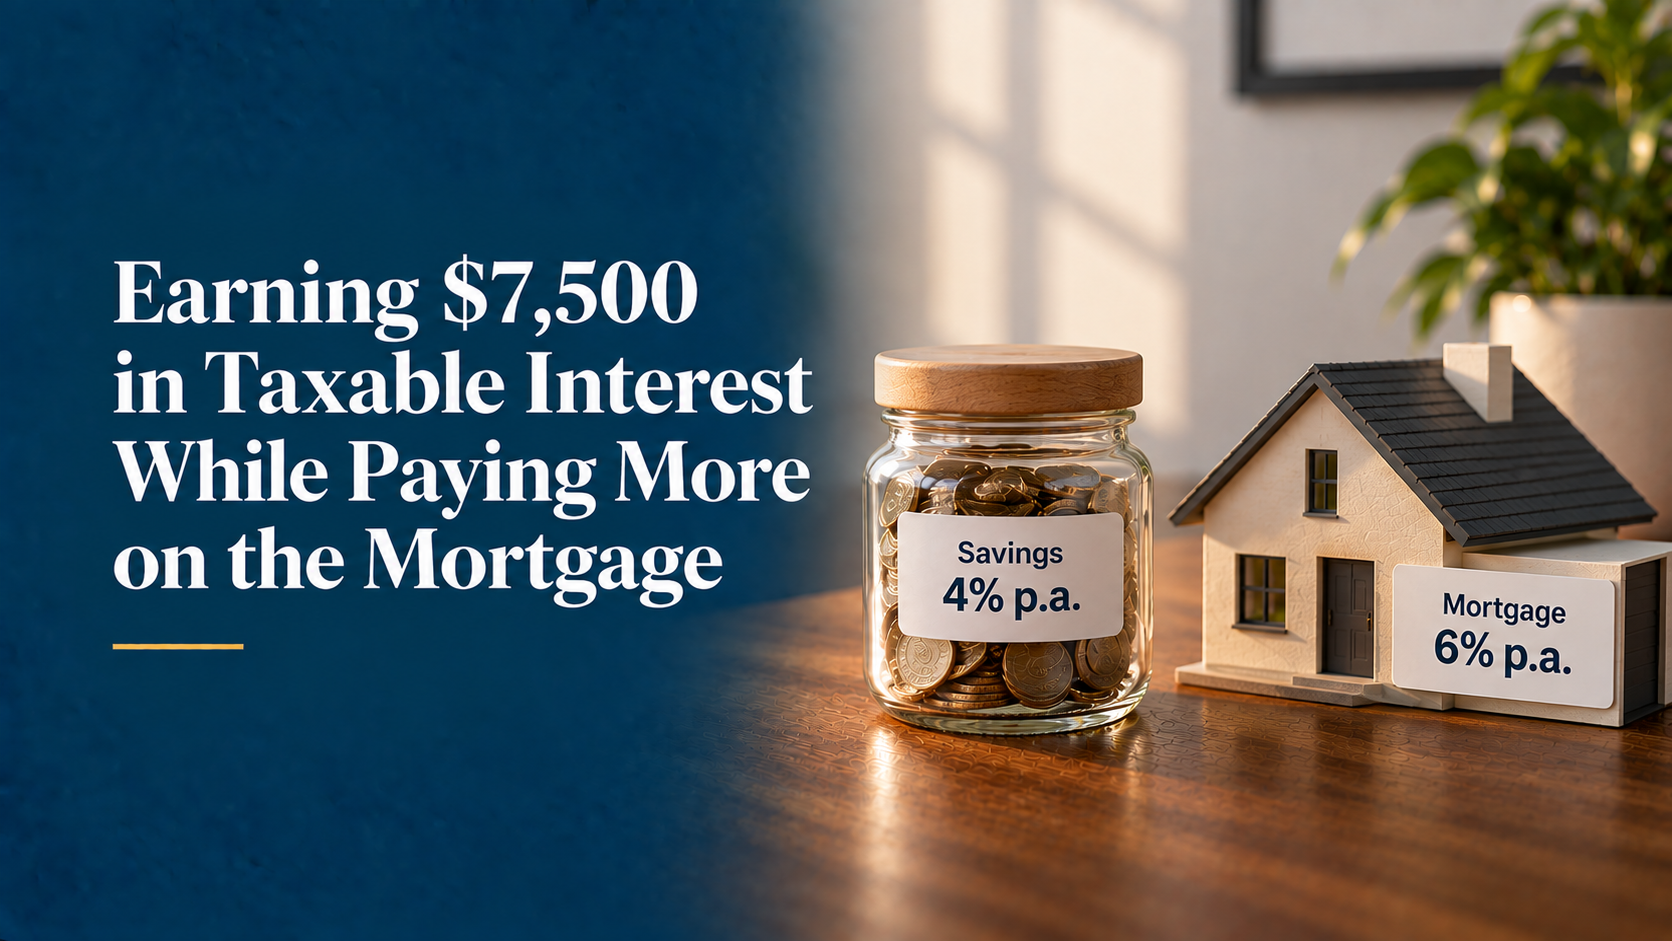
Earning $7,500 in Taxable Interest While Paying More on the Mortgage
Sometimes improving a client's financial position isn't aboutfinding another tax deduction.
It's about looking at the whole picture.
We had a client earning approximately $7,500a year in bank interest fromcash they were holding separately. At first glance, earning interest soundslike a good thing.
But when we looked at their broader position, we noticed somethingimportant: they also had a home mortgage.
Together with an appropriately licensed financial adviser, weconsidered a simple question:
Why was the client earning a lower rate of interest on theirsavings while paying a higher rate of interest on their mortgage?
The comparison wasn't simply 4%versus 6%
Suppose the client's savings were earning approximately 4%, whiletheir home loan was costing approximately 6%.
Earning $7,500 at 4% implies savings of around $187,500.At a 6% mortgage rate, having that same amount effectively offset against thehome loan could potentially reduce mortgage interest by approximately $11,250per year, assuming the rates and balances remained unchanged.
But there was another consideration.
The $7,500 of bank interest was assessableincome. For a client on a higher marginal tax rate, part ofthat return would be lost to income tax.
So, the real comparison wasn't simply:
4% savings interest versus 6% mortgage interest.
It was the client's after-tax return on their savingscompared with the interest cost of their private home loan.
Interest avoided on a private home mortgage doesn't itself createadditional assessable income. This meant the difference could be considerablygreater than the headline interest rates initially suggested.
The opportunity was surprisinglysimple
After considering the client's circumstances with their financialadviser, one option was to hold the cash in an appropriate mortgageoffset account ratherthan a separate interest-bearing savings account.
The cash remained available to the client, but instead of earningtaxable interest at a lower rate, it could reduce the balance on whichhome-loan interest was calculated.
It wasn't a complicated investment strategy or an obscure taxconcession.
It was simply about asking whether the client's cash and debt wereworking efficiently together.
There is also an important distinction between an offsetaccount and paying money directly into a loan with a redraw facility.Redrawing previously repaid amounts can have different tax consequences becausea redraw is generally treated as a new borrowing. This can become particularlyimportant if the property is later used to produce assessable income.
That is why the appropriate loan structure needs to be consideredbefore simply moving the money.
Making cash and debt work together
The important question wasn't simply how much tax the client waspaying on their interest income. It was whether their cash and debt wereworking efficiently together.
The client was earning a lower rate of taxable interest on theirsavings while paying a higher rate of non-deductible interest on their homemortgage. Looking at both sides of the balance sheet exposed an opportunitythat wasn't obvious from either item in isolation.
As tax advisers, our role was to identify the tax consequences andhighlight the opportunity. Because the decision also involved the client'sdebt, liquidity and broader financial position, we worked alongside anappropriately licensed financial adviser.
Sometimes the opportunity isn't hidden in the tax legislation.It's sitting in the client's bank account.
Thiscase study has been generalised, and certain details have been changed toprotect client confidentiality. General information only. The appropriate useof savings, offset accounts and redraw facilities depends on individualcircumstances and lending arrangements. Redraw and offset arrangements can havematerially different tax consequences, particularly where a property maysubsequently become income-producing. Our role was to advise on the taxationconsequences and identify the opportunity. Financial product advice may requireadvice from an appropriately licensed financial adviser, while lending andcredit matters may require advice from an appropriately licensed creditadviser.
Medicare Levy Surcharge: When Private Hospital Cover Cost Less Than the Tax
Sometimes a tax return shows us a cost that doesn't necessarilyneed to keep occurring.
We had a higher-income client who was paying the MedicareLevy Surcharge (MLS) because they and their spouse didn't haveappropriate private hospital cover. Rather than simply calculating thesurcharge again and moving on, we raised a simple question:
“Have you considered the cost of appropriate private hospitalcover compared with the Medicare Levy Surcharge you're paying?”
They were paying extra taxevery year
The Medicare Levy Surcharge is separate from the ordinary Medicarelevy. Depending on income and family circumstances, higher-income taxpayerswithout appropriate private patient hospital cover can pay an additional 1%to 1.5% of their income for MLS purposes.
For a higher-income family, that can become a significantrecurring cost. But the client had never really compared the cost of thesurcharge against the cost of obtaining appropriate private hospital cover.
We suggested they investigate their options. After obtainingquotes for appropriate hospital cover for both husband and wife,they discovered that the cost of the cover was less than the MedicareLevy Surcharge they would otherwise be paying.
With appropriate cover in place, they could eliminate their MLSexposure for the periods they were appropriately covered, subject to continuingto satisfy the relevant requirements. The ordinary Medicare levy remainedseparate and was not eliminated.
Recurring tax costs areworth questioning
When the same additional tax cost appears yearafter year, it's worth understanding why it's arising and whether the clienthas options.
In this case, the Medicare Levy Surchargewasn't an unavoidable annual cost. Once the client understood why it was beingimposed, they could compare that cost with the cost of appropriate privatehospital cover and make an informed decision about what suited theircircumstances.
Sometimes the importantquestion isn't “How much tax do I owe?” It's “Why am I paying this every year?”
General information only. The Medicare Levy Surcharge is separatefrom the ordinary Medicare levy. MLS liability depends on income for MLSpurposes, family circumstances, dependants and whether appropriate privatepatient hospital cover is held for the relevant period. The cost, suitability,benefits and terms of private health insurance should be considered by theclient with the insurer or an appropriately qualified adviser.
Rental Property Depreciation: The Question That Improved the Client’s Tax Position by $17,816
Achieving a better tax outcome doesn't require a complicatedstrategy.
Sometimes it starts with asking one simple question.
A new client came to us after previously having their tax returnsprepared elsewhere. They owned a rental property, so as part of our review weasked: “Do you have a depreciation scheduleprepared by a quantity surveyor?”
They didn't, and this was something that had not previously beenraised with them. We recommended that they consider engaging a qualifiedquantity surveyor to assess the property and prepare a depreciation schedule.They did — and the results were significant.
From $8,345 payable to arefund
Before our review, the client's 2025 tax position showedapproximately $8,345 payable to the ATO.After the depreciation schedule was prepared and the client's tax position wasreviewed, the result changed to an approximately $1,865refund.
That's a turnaround of approximately $10,210for the 2025 income year alone.
But we didn't stop there. Once the depreciation schedule had beenprepared, we considered whether the client had also missed deductions in theprevious income year. We reviewed their 2024 tax return and identified anopportunity to amend it.
The client had previously paid approximately $5,430to the ATO for 2024. Based on the revised position, they couldrecover that amount and receive an additional refund of approximately$2,177, improving the client's 2024 tax position byapproximately $7,606.
Across the two income years, the overall improvement in theclient's tax position was approximately $17,816.
In cash-flow terms, instead of paying the ATO another $8,345, theclient moved to receiving refunds and recovered tax totalling approximately $9,471.
And the process started with one question: “Doyou have a depreciation schedule?”
The review mattered
Clients don'tnecessarily know every deduction that may be available to them. That's whypreparing a tax return properly involves more than entering the informationprovided — it also means reviewing the client's circumstances and identifyingareas that warrant further investigation.
In this case, one missing depreciation scheduleultimately contributed to an approximately $17,816 improvement in the client's taxposition across two years.
The opportunity wasidentified because the review went beyond the figures already appearing in thereturn.
General information only. Eligibility for depreciation deductionsdepends on the property, taxpayer, acquisition date, expenditure and othercircumstances. A quantity surveyor's report does not itself determine taxdeductibility, and the tax treatment of identified amounts must be consideredunder the applicable tax law.
How Two Months Potentially Saved a Client Around $70,000 in Tax
Sometimes significant tax savings don't come from complicated taxstructures. They come from asking the right question at the righttime.
A client was considering selling an asset that had increasedsubstantially in value. Before putting it on the market, they called us todiscuss the potential tax implications and asked:
“If I sell this, what am I going to be up for in tax?”
As part of that conversation, we asked about the expected saleprice, cost base, associated costs and, importantly:
“When did you acquire it?”
That last question changed the conversation.
They had only owned it for 10 months
The client had owned the asset for approximately 10months.
Eligible individuals and trusts can generally access the 50%CGT discount wherethey have held a CGT asset for at least 12 months, and the other requirementsare satisfied.
Our client was potentially only two months away from qualifying.
There was no commercial need to sell immediately, so rather thansimply calculating the tax consequences of selling now, we discussed whetherthey should consider waiting until the 12-month ownership requirement had beensatisfied before entering into a sale.
What could two months be worth?
The asset was expected to produce an approximately $300,000capital gain.
Under a simplified example, assuming there were no capital lossesto apply, and the client otherwise qualified for the 50% CGT discount, thecapital gain remaining after the discount could reduce from $300,000to $150,000.
For an individual whose additional taxable income would otherwisebe subject to the highest marginal tax rate, including Medicare levy, that$150,000 difference could represent approximately $70,500— or around $70,000 — in tax.
That wasn't because we implemented an aggressive tax structure oranything particularly complicated.
We simply asked:
“When did you buy it?”
Timing matters
There is another important point. For a typical disposal under acontract, the CGT event generally occurs when the contractis entered into, rather than when settlement occurs.
So, this isn't necessarily something that can be solved by signinga contract before satisfying the 12-month requirement and simply arrangingsettlement for later.
That is why having the conversation beforethe client committed to the sale mattered.
Had the client entered into the sale first and sought adviceafterwards, the opportunity to potentially access the 50% CGT discount mayalready have been lost.
In this case, approximately two months potentially made adifference of around $70,000.
For significant transactions, the timing of the tax conversationcan materially change the outcome. Sometimes the most valuable advice happensbefore the transaction occurs.
General information only. CGT outcomes depend on thetaxpayer, asset, residency, acquisition and disposal dates, capital losses andother circumstances. This is a simplified example assuming the taxpayer is anAustralian-resident individual, has no relevant capital losses, qualifies forthe 50% CGT discount and the relevant additional taxable income is subject tothe highest marginal tax rate plus Medicare levy. Companies are not generallyentitled to the 50% CGT discount.
Term Deposit or FMD? A Tax Planning Lesson for Primary Producers
There is a big difference between preparing a tax return andproviding proactive tax advice.
We recentlyreviewed the position of a farming client who had consistently been paying taxat relatively high marginal rates. The business was profitable and, when therewas surplus cash, the client did what many people would naturally do: theyput the money into ordinary term deposits.
There was nothinginherently wrong with that decision. But given the client was a primaryproducer, there was another tax-planningopportunity worth considering: Farm Management Deposits.
The opportunity: FarmManagement Deposits
One strategy we discussed was the Farm Management Deposit(FMD) Scheme. Broadly, an eligible primary producer can deposit money intoan FMD and claim a tax deduction for the amount deposited, subject to therelevant requirements and limits.
When the FMD is later withdrawn, the amount previously deductedgenerally becomes assessable income. This means an FMD is primarily a taxdeferral and income-smoothing strategy, rather than a way of permanentlyeliminating taxable income.
That can be particularly valuable in farming, where income canfluctuate considerably because of seasonal conditions, commodity prices, inputcosts and other factors.
Consider a simple example
Suppose an eligible farmer has a particularly profitable yearand $100,000 of surplus cash. They could put the money into anordinary term deposit, but the deposit itself doesn't produce a $100,000 taxdeduction.
Alternatively, subject to satisfying the FMD requirements,depositing the $100,000 into an FMD could potentially provide a $100,000tax deduction in the year of deposit. When the FMD is later withdrawn, theamount previously deducted generally becomes assessable income.
The potential benefit is therefore in the timing. Ifan FMD is deposited during a high-income year and withdrawn during asignificantly lower-income year, it can help smooth taxable income acrossdifferent years while preserving cash for when the farming business needs it.
FMDs have importanteligibility requirements
FMDs aren't available to everyone. Among other requirements, thereare rules concerning who can hold an FMD, the amount of non-primary-productionincome the taxpayer can have, how much can be deducted, the maximum FMD balanceand how long the deposit generally needs to be held.
For example, the total amount generally held in FMDs cannotexceed $800,000, and the taxpayer's taxable non-primary-productionincome generally needs to be less than $100,000 in therelevant income year. The particular farmer's eligibility and circumstancestherefore need to be reviewed before implementing the strategy.
The planning opportunitycomes before tax time
An accountant can prepare a completely correct tax return based ondecisions the client has already made. If the client says, “We put$100,000 into a term deposit,” the accountant can record the interest,prepare the financial statements and lodge a technically correct tax return.
But nobody may have asked whether the $100,000 should have goneinto an ordinary term deposit in the first place.
That's where proactive tax planning can make a difference. By thetime the tax return is being prepared, many planning opportunities may alreadyhave passed.
Good tax advice shouldn't only ask, “What did you do lastyear?” It should also ask, “What are you planning to do, andis there a more tax-effective way of doing it?”
The value was identifyingthe planning opportunity while the client still had a choice about where thesurplus cash went.
Generalinformation only. Farm Management Deposits are subject to detailed eligibilityrequirements and tax rules. The appropriate strategy depends on the taxpayer'sindividual circumstances.
Stay Ahead with Business & Tax Insights
Receive practical business insights, taxation updates and strategic guidance delivered directly to your inbox. Stay informed about legislative changes, emerging opportunities and practical strategies to help you structure, grow and protect your business.
Recognised professional credentials and technology partnerships that demonstrate our commitment to technical excellence and ongoing professional development.
Don't wait until tax time to ask the important questions.
The Tax Bar Australia provides proactive tax and business advice designed to help you make informed decisions before opportunities are missed or problems arise.