Keeping your salary relatively low can sometimes make sense when you operate through a company and don't need all of the business profits personally.
But what happens when you actually need the money?
We had a client operating a successful business through a company. They had historically taken a relatively modest salary and left a significant amount of profit and cash inside the company.
Then their circumstances changed: they wanted to purchase an investment property and needed additional personal cash to help fund it.
Rather than simply continuing with the same salary strategy, we reviewed the client's broader position — including accumulated company profits, available cash, franking credits, Division 7A and the tax consequences of extracting additional profits.
How should the money come out of the company?
The first question wasn't simply, “How much money can we take out?”
It was, “What's the appropriate way to extract it?”
We considered the relative consequences of additional salary versus franked dividends. Salary may generally be deductible to the company but can also have PAYG withholding, superannuation and other consequences. Dividends aren't deductible to the company, but where the company has sufficient franking credits, those credits can potentially be attached to dividends and recognised in the shareholder's personal tax position.
In this client's circumstances, we considered a planned dividend strategy, including interim dividends during the financial year where appropriate, rather than waiting until year-end to decide how much money should be extracted.
That provided the client with additional personal cash that could be put towards the proposed investment property purchase.
Working backwards from the cash the client actually needed
Simply declaring a $100,000 dividend doesn't necessarily mean the client has $100,000 available to spend without further tax consequences.
A fully franked dividend generally comes with a franking credit representing company tax already paid. The cash dividend plus the franking credit is generally included in the shareholder's assessable income, with a corresponding franking tax offset. Depending on the client's overall taxable income and marginal tax rate, additional personal tax may still be payable.
So we worked backwards from the client's objective. How much cash did they actually need for the property purchase? How much should be distributed? What franking credits were available? And what additional personal tax could arise?
That gave the client a much clearer understanding of the after-tax cash actually available for the investment, rather than simply looking at the balance in the company bank account.
Avoiding an unintended Division 7A problem
This planning was also important because company money isn't automatically the shareholder's personal money.
Simply transferring company cash to a shareholder to fund a private investment can potentially create Division 7A consequences if the amount isn't otherwise appropriately dealt with. Depending on the circumstances, a payment or loan by a private company to a shareholder or associate can potentially result in an unfranked deemed dividend.
So instead of saying, “The company has the cash — use it for the deposit,” we considered how the money should legitimately be extracted before it was used.
In this case, properly declared franked dividends allowed us to plan the distribution of accumulated company profits while taking the available franking credits into account.
That's very different from withdrawing the money first and worrying about the tax consequences later.
Looking at the property and dividends together
The investment property would also change the client's personal tax position.
Once the property was held for income-producing purposes, eligible expenses could potentially include interest on investment borrowings, council rates, property management fees, insurance, certain repairs and maintenance, capital works deductions and depreciation on eligible depreciating assets.
Where allowable rental deductions exceed rental income, the resulting net rental loss may generally reduce the client's other taxable income, subject to the normal tax rules.
That was relevant because the planned dividends would increase the client's assessable income. Rather than considering the dividend strategy and investment property in isolation, we modelled how the different components would interact in the client's overall tax position.
Importantly, negative gearing wasn't the reason to purchase the property. A tax deduction only reduces part of an economic cost, and the investment itself still needed to make commercial sense.
Tax planning should respond to what the client is trying to achieve
If we had looked only at the client's salary, we might simply have continued with the existing approach. If we had looked only at the company, we might have focused on leaving profits inside it.
But neither approach answered the more important question:
What was the client actually trying to achieve?
They wanted to purchase an investment property.
That meant considering salary versus dividends, available franking credits, how much after-tax cash they actually needed, Division 7A before accessing company funds, and the tax consequences of the proposed investment property.
Tax planning shouldn't happen in isolation from the client's objectives. A strategy that made sense when the client didn't need the cash needed to be reconsidered when their circumstances changed.
This case study has been generalised, and certain details have been changed to protect client and business confidentiality. General information only. Dividend, franking, Division 7A, salary, superannuation and rental-property consequences depend on the particular circumstances. Our role was to advise on the taxation consequences of the proposed arrangements. Investment decisions and financial product advice may require advice from an appropriately licensed financial adviser, while lending and credit matters may require advice from an appropriately licensed credit adviser.
Stay Ahead with Business & Tax Insights
Receive practical business insights, taxation updates and strategic guidance delivered directly to your inbox. Stay informed about legislative changes, emerging opportunities and practical strategies to help you structure, grow and protect your business.
More real-world examples
Explore other situations where a closer look at the numbers, structure or timing helped uncover an opportunity or identify a potential issue.
The Hospitality Business Was Turning Over $1.5 Million — But Nobody Knew What It Was Making Each Month
A hospitality business was turning over approximately $1.5 million a year.
Sales were strong. The business was busy. Staff were working.
But there was a fundamental problem:
The owners couldn't clearly see what the business was actually making each month.
The bookkeeping was being completed, but the accounts weren't producing reliable monthly management information.
Before we could talk about improving profitability, we first needed numbers we could trust.
First, we fixed the numbers
We reviewed the bookkeeping and month-end processes and identified several issues affecting the accuracy of the monthly results.
Among other things, we:
· moved equipment purchases that had incorrectly been expensed through the profit and loss statement to the balance sheet where appropriate;
· cleaned up the chart of accounts so revenue, cost of goods sold and operating expenses could be properly analysed;
· introduced tracking categories to provide better visibility over the business;
· developed proper month-end procedures;
· brought cash sales and undeposited cash into the accounts;
· reconciled uncleared sales amounts from Epos Now; and
· accrued wages into the correct reporting periods.
None of these changes, by themselves, were the objective.
The objective was to produce financial information that actually showed what was happening in the business each month.
Once the accounts were reliable, we could start asking better questions.
Then we benchmarked the business
We didn't just compare this month with last month.
We compared the business against external industry information, including specialist industry benchmarking reports, ATO small business benchmarks and IBISWorld industry research, where relevant.
We considered measures such as cost of goods sold, gross margins, labour costs, overheads, net profit margins and sales patterns.
Benchmarking wasn't the answer by itself.
It helped us identify where the business was performing differently and where we needed to investigate further.
We could then work through the underlying drivers of profitability - including purchasing and cost of goods sold, labour efficiency, pricing, operating hours, overheads and other areas affecting margins.
For example, one area we investigated was labour.
Rather than simply looking at the total annual wage bill, we asked:
Were all of the hours the business was open actually profitable?
By comparing sales patterns across different operating hours with the staffing required during those periods, we could identify times when the business was generating revenue but potentially very little profit after labour and other operating costs.
That gave the owners a better basis for making decisions about staffing levels and operating hours.
We also looked at cost of goods sold and gross margins.
One of the areas reviewed was the cost of providing free meals to staff. The business moved from providing free staff meals to a discounted arrangement, among other changes designed to improve the amount of gross profit retained from each dollar of sales.
These were only some of the areas addressed.
The broader objective was to understand what was driving profitability and identify practical changes that could improve the bottom line.
Revenue wasn't the problem
A business turning over $1.5 million can still underperform.
The objective wasn't simply to increase sales.
It was to improve the amount of profit being retained from the sales the business was already generating.
Reliable monthly reporting gave us the starting point. Benchmarking helped identify where to look. More detailed analysis helped identify what could actually be changed.
Following the changes to the financial reporting and the operational decisions that came from the analysis, within a few months, net profit had increased by approximately 7%.
The improved profitability and reporting also gave us a much clearer basis for considering remuneration for the working directors, rather than making those decisions without reliable information about the underlying performance and cash requirements of the business.
Bookkeeping should tell you something
Accurate bookkeeping is essential.
But for a growing business, getting the transactions into the accounting system is only the starting point.
Good monthly reporting should help answer questions such as:
What is actually driving our profit?
How do our margins compare with similar businesses?
Where are we losing margin?
Are our wages appropriate for the sales we're generating?
Are all of our operating hours commercially worthwhile?
What can we change to improve the bottom line?
Because the goal isn't simply to have higher revenue.
The goal is to build a more profitable business.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. Benchmarking information should be considered in the context of the particular business and should not be treated as a substitute for analysis of its actual circumstances.
The Tax Planning Worked — Until the Division 7A Repayments Reached $120,000 a Year
For several years, a business owner had been managing their personal taxable income while regularly redrawing money from their private company.
The strategy worked when viewed one year at a time.
Their salary was being managed so that their personal taxable income remained around the 30% marginal tax bracket, while additional amounts drawn from the company accumulated as Division 7A loans.
The loans had been put on complying terms.
But the balances weren't disappearing.
As the loans accumulated over several years, so did the minimum yearly repayment obligations.
Eventually, the client's combined minimum yearly repayments had reached approximately $120,000 a year.
Where those repayments were being dealt with through dividends from the company, the dividends, together with the client's existing salary, were now pushing part of their taxable income into the 45% marginal tax bracket.
The tax planning had worked in the earlier years.
But eventually, it started to catch up.
The tax had been deferred — not eliminated
A complying Division 7A loan can prevent an amount from being treated as a deemed dividend at the time the loan is made, provided the relevant requirements are satisfied.
But putting a loan on complying terms doesn't make the debt disappear.
Interest accrues and minimum yearly repayments generally need to be made over the term of the loan.
For several years, the strategy had allowed the client to access additional company funds while managing their immediate personal taxable income.
The problem became apparent when we looked at the position over multiple years rather than one financial year at a time.
Each additional loan created another future obligation.
Eventually, the accumulated minimum yearly repayments had reached approximately $120,000 a year. Where those repayments were being dealt with through dividends from the company, the taxable income required to service the loans, together with the client's salary, was now pushing part of their income into the 45% marginal tax bracket.
What had appeared to be tax minimisation in the earlier years was, to a significant extent, tax deferral.
The problem wasn't the Division 7A loan agreement
The loans had been put on complying terms.
So simply preparing another loan agreement or calculating another minimum yearly repayment wasn't the answer.
The bigger issue was that the strategy had been repeated without sufficient consideration of where the accumulated loans would eventually lead.
The client was also continuing to redraw money from the company.
That created the possibility of repaying old Division 7A loans while simultaneously creating new ones.
So we needed to look beyond the annual compliance requirements and consider the client's broader strategy for extracting money from the company.
That meant considering the existing loan balances, future personal cash requirements, salary, available franking credits, company cash flow and how the loans could progressively be reduced without simply allowing the same cycle to continue.
Tax planning shouldn't stop at 30June
A strategy that reduces taxable income today can still create obligations that need to be dealt with tomorrow.
In this case, the issue wasn't that Division 7A had been ignored.
The issue was that the strategy had been repeated without sufficient consideration of where the accumulated loans would eventually lead.
Good tax planning therefore asks more than:
“What does this save this year?”
It should also ask:
“Where does this leave the client five or seven years from now?”
Because sometimes the tax hasn't disappeared.
It's simply been deferred to another year.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. General information only. Division 7A outcomes depend on the particular payments, loans, agreements, repayments, timing and other circumstances involved.
The Salon Was Making Money — So Where Was the Rent?
Sometimes the numbers that are missing from a set of accounts can be just as important as the numbers that are there.
We were reviewing the tax position of a sole trader operating a salon business. The business was generating revenue and had the usual expenses associated with providing its services.
But one thing stood out.
There was no rent or other premises expense.
A salon has to operate somewhere.
So before simply preparing the tax return from the figures provided, we asked:
“Where are you actually operating the salon from?”
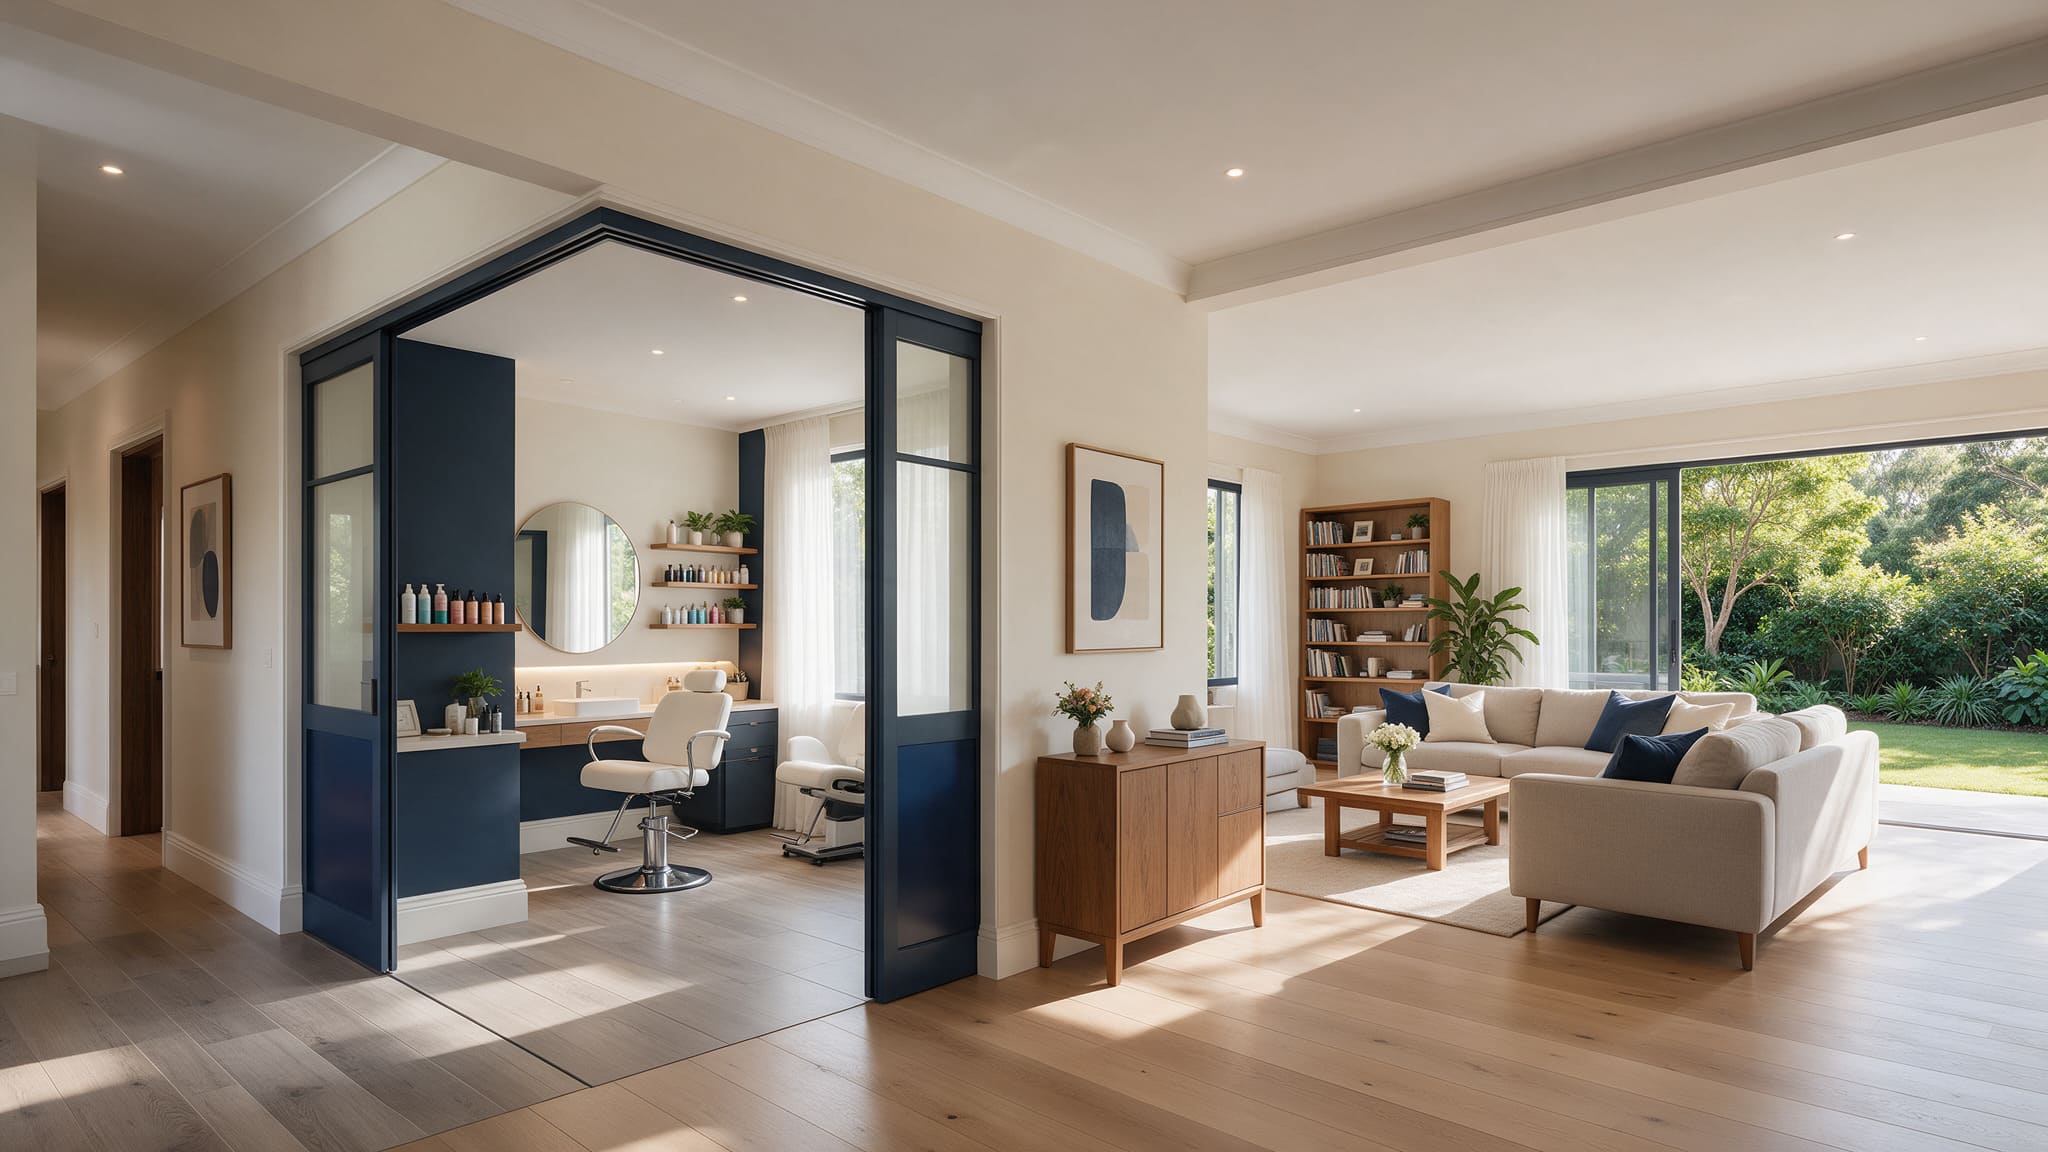
The business was operating from a dedicated room at home
The client explained that they were renting their home and had a separate room set aside for operating the salon.
That changed the tax analysis.
For a sole trader operating a business from home, there is an important distinction between simply doing some administrative work from home and having part of the home that genuinely has the character of a place of business.
In this case, the separate room was being used for the salon business.
That meant we needed to consider whether an appropriate proportion of the client's rent could be claimed as an occupancy expense, together with relevant running expenses associated with operating the business from the property.
The deduction wasn't automatically the entire rent. The business and private use of the property needed to be appropriately separated, and the claim supported by the client's circumstances and records.
Rent wasn't the only expense worth reviewing
Once we understood where the business was actually operating, the conversation went beyond rent.
We also considered whether an appropriate business portion of other costs associated with operating the salon from the rented home had been captured, such as electricity, cleaning and other relevant household running expenses.
The objective wasn't to find expenses to claim simply because the client worked from home.
It was to establish what it genuinely cost to operate the salon from the property and make sure the deductible portion of those costs was properly considered.
Sometimes the missing number is the clue
If we had simply taken the bookkeeping at face value, the tax return could have been prepared using the expenses already recorded.
But the profit and loss statement told us something didn't quite make commercial sense.
The business was operating a salon.
Where was the cost of the premises?
That simple question led us to understand how the business actually operated and identify expenses that warranted further investigation.
Good tax review isn't only about checking whether the numbers provided are correct.
Sometimes it's about recognising which number should logically be there — but isn't.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. General information only. Home-based business deductions depend on the taxpayer's circumstances and the nature and use of the relevant area. Occupancy expenses such as rent are generally only available where the relevant part of the home has the character of a place of business. Business and private expenses must be appropriately apportioned and substantiated. Different considerations can apply where the business is operated through a company or trust rather than by a sole trader.