During a conversation with a client, they mentioned that an estatewas in the process of being finalised.
They expected to receive approximately $2million of inherited assets, including shares, interests inresidential property, investment properties, physical gold and otherinvestments.
None of the assets were necessarily being sold.
They were simply passing to the client as part of the estate.
It would therefore have been easy to think:
“There's nothing we need to do until I eventually sell them.”
But that was exactly why we raised an important question:
What tax history needs to come with the assets?
The Cost Base Isn't Always the Value You Inherit
Receiving an asset worth $500,000 doesn't necessarily mean$500,000 becomes its cost base for CGT purposes.
The treatment can differ significantly from one inherited asset to another.
Depending on the circumstances, the beneficiary may effectivelyinherit the deceased's existing cost-base history. In other situations, market value at the date of death can become relevant — including for certain assets acquired by the deceased before the introduction of CGT and certain qualifying inherited dwellings.
That meant we couldn't simply record:
“Inherited assets — approximately $2 million.”
We needed to look at the assets individually.
When did the deceased acquire them? What did they originally pay?Were they acquired before or after the introduction of CGT? What subsequentcosts and improvements were incurred? Was a property the deceased's mainresidence? Was it being used to produce income? Was a date-of-death valuationrequired?
Those questions could materially affect the eventual CGT calculation.
The Residential Property Raised Another Question
The inherited residential property also required separateconsideration.
Special CGT rules can apply to a dwelling inherited from a deceased estate, including circumstances where a full main-residence exemption may be available if the relevant ownership interest is disposed of within two years of the deceased's death, subject to the particular conditions.
That made the estate-administration period relevant for more than simply collecting records.
There could also be a time-sensitive tax consideration around what ultimately happened with the property.
Rather than discovering that issue several years later, it could be considered while the estate was still being administered and the relevantinformation was readily available.
Get the Records While They're Available
We recommended obtaining and retaining the relevant tax history aspart of the estate process.
Depending on the particular asset, that could include:
· original acquisitionrecords;
· historical share andinvestment statements;
· details of subsequentpurchases and disposals;
· records of capitalimprovements and other relevant expenditure;
· information about howproperties had been used;
· relevant estatedocumentation; and
· date-of-death valuationswhere the tax rules made market value relevant.
This mattered because the client might hold some of these assetsfor another 10, 20 or 30 years.
By the time they're eventually sold, the executor, lawyers,accountants, investment providers or family members currently dealing with theestate may no longer have the records readily available.
Reconstructing decades of tax history at that point can beconsiderably more difficult.
And the Assets Don't Just Create a Future CGT Issue
Some of the inherited assets could also begin affecting the client's tax position immediately.
Shares may produce dividends and franking credits.
Investment properties may produce rentalincome and deductible expenses.
Other investments may generate income or havetheir own record-keeping requirements.
So the tax conversation shouldn't necessarilybegin when an inherited asset is eventually sold.
For this client, it began when the assets were being inherited.
Preserve the tax history while the records are available
Receiving an inheritance isn't just about determining what assetsyou're getting and what they're worth today.
For significant inherited assets, another important question is:
“What tax history needs to come with them?”
A portfolio worth approximately $2 million today may eventually be worth substantiallymore.
If an asset is sold decades later, having the correct acquisition history, supporting expenditure and relevant valuations could make an enormous difference to how confidently and accurately the capital gain can be calculated.
That's why we don't want a client coming to us 20 years later witha sale contract and saying:
“I inherited this years ago, but I have no idea what the cost base is.”
Sometimes good tax planning isn't about reducing today's tax.
It's making sure theinformation needed to calculate tomorrow's tax isn't lost today.
The CGT treatment and cost base of inherited assets depend on the particular asset and circumstances, including when and how the deceased acquired it, its use, the circumstances at the date of death and the circumstances of the estate and beneficiary. Special rules apply toinherited dwellings, including the deceased-estate main residence provisions.Financial amounts and certain details have been generalised to protectconfidentiality.
Stay Ahead with Business & Tax Insights
Receive practical business insights, taxation updates and strategic guidance delivered directly to your inbox. Stay informed about legislative changes, emerging opportunities and practical strategies to help you structure, grow and protect your business.
More real-world examples
Explore other situations where a closer look at the numbers, structure or timing helped uncover an opportunity or identify a potential issue.
The Hospitality Business Was Turning Over $1.5 Million — But Nobody Knew What It Was Making Each Month
A hospitality business was turning over approximately $1.5million a year.
Sales were strong. The business was busy. Staff were working.
But there was a fundamental problem:
The owners couldn't clearly see what the business was actuallymaking each month.
The bookkeeping was being completed, but the accounts weren'tproducing reliable monthly management information.
Before we could talk about improving profitability, we firstneeded numbers we could trust.
First, we fixed the numbers
We reviewed the bookkeeping and month-end processes and identifiedseveral issues affecting the accuracy of the monthly results.
Among other things, we:
· moved equipment purchasesthat had incorrectly been expensed through the profit and loss statement to thebalance sheet where appropriate;
· cleaned up the chart ofaccounts so revenue, cost of goods sold and operating expenses could beproperly analysed;
· introduced trackingcategories to provide better visibility over the business;
· developed proper month-endprocedures;
· brought cash sales andundeposited cash into the accounts;
· reconciled uncleared salesamounts from Epos Now; and
· accrued wages into thecorrect reporting periods.
None of these changes, by themselves, were the objective.
The objective was to produce financial information that actuallyshowed what was happening in the business each month.
Once the accounts were reliable, we could start asking betterquestions.
Then we benchmarked the business
We didn't just compare this month with last month.
We compared the business against external industry information,including specialist industry benchmarkingreports, ATO small business benchmarks and IBISWorld industry research,where relevant.
We considered measures such as cost of goods sold, gross margins,labour costs, overheads, net profit margins and sales patterns.
Benchmarking wasn't the answer by itself.
It helped us identify where the business was performingdifferently and where we needed to investigate further.
We could then work through the underlying drivers of profitability— including purchasing and cost of goods sold, labour efficiency, pricing,operating hours, overheads and other areas affecting margins.
For example, one area we investigated was labour.
Rather than simply looking at the total annual wage bill, weasked:
Were all of the hours the business was open actually profitable?
By comparing sales patterns across different operating hours withthe staffing required during those periods, we could identify times when thebusiness was generating revenue but potentially very little profit after labourand other operating costs.
That gave the owners a better basis for making decisions aboutstaffing levels and operating hours.
We also looked at cost of goods sold and gross margins.
One of the areas reviewed was the cost of providing free meals tostaff. The business moved from providing free staff meals to a discountedarrangement, among other changes designed to improve the amount of gross profitretained from each dollar of sales.
These were only some of the areas addressed.
The broader objective was to understand what was drivingprofitability and identify practical changes that could improve the bottomline.
Revenue wasn't the problem
A business turning over $1.5 million can still underperform.
The objective wasn't simply to increase sales.
It was to improve the amount of profit being retained from thesales the business was already generating.
Reliable monthly reporting gave us the starting point.Benchmarking helped identify where to look. More detailed analysis helpedidentify what could actually be changed.
Following the changes to the financial reporting and theoperational decisions that came from the analysis, withina few months, net profit had increased by approximately 7%.
The improved profitability and reporting also gave us a muchclearer basis for considering remuneration for the working directors, ratherthan making those decisions without reliable information about the underlyingperformance and cash requirements of the business.
Bookkeeping should tell yousomething
Accurate bookkeeping is essential.
But for a growing business, getting the transactions into theaccounting system is only the starting point.
Good monthly reporting should help answer questions such as:
What is actually driving our profit?
How do our margins compare with similar businesses?
Where are we losing margin?
Are our wages appropriate for the sales we're generating?
Are all of our operating hours commercially worthwhile?
What can we change to improve the bottom line?
Because the goal isn't simply to have higher revenue.
The goal is to build a more profitable business.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. Benchmarking information should be considered in the context of the particular business andshould not be treated as a substitute for analysis of its actual circumstances.
The Tax Planning Worked — Until the Division 7A Repayments Reached $120,000 a Year
For several years, a business owner had been managing theirpersonal taxable income while regularly redrawing money from their privatecompany.
The strategy worked when viewed one year at a time.
Their salary was being managed so that their personal taxableincome remained around the 30% marginal tax bracket,while additional amounts drawn from the company accumulated as Division 7Aloans.
The loans had been put on complying terms.
But the balances weren't disappearing.
As the loans accumulated over several years, so did the minimumyearly repayment obligations.
Eventually, the client's combined minimum yearly repayments hadreached approximately $120,000 a year.
Where those repayments were being dealt with through dividends from the company, the dividends, together with the client's existing salary,were now pushing part of their taxable income into the 45% marginal tax bracket.
The tax planning had worked in the earlier years.
But eventually, it started to catch up.
The tax had been deferred — not eliminated
A complying Division 7A loan can prevent an amount from being treated as a deemed dividend at the time the loan is made, provided the relevant requirements are satisfied.
But putting a loan on complying terms doesn't make the debt disappear.
Interest accrues and minimum yearly repayments generally need tobe made over the term of the loan.
For several years, the strategy had allowed the client to accessadditional company funds while managing their immediate personal taxableincome.
The problem became apparent when we looked at the position overmultiple years rather than one financial year at a time.
Each additional loan created another future obligation.
Eventually, the accumulated minimum yearly repayments had reached approximately $120,000 a year. Where those repayments were being dealt with through dividends from the company, the taxable income required to service the loans, together with the client's salary, was now pushing part of their income into the 45%marginal tax bracket.
What had appeared to be tax minimisation in the earlier years was,to a significant extent, tax deferral.
The problem wasn't the Division 7A loan agreement
The loans had been put on complying terms.
So simply preparing another loan agreement or calculating anotherminimum yearly repayment wasn't the answer.
The bigger issue was that the strategy had been repeated withoutsufficient consideration of where the accumulated loans would eventually lead.
The client was also continuing to redraw money from the company.
That created the possibility of repaying old Division 7A loans whilesimultaneously creating new ones.
So we needed to look beyond the annual compliance requirements andconsider the client's broader strategy for extracting money from the company.
That meant considering the existing loan balances, future personalcash requirements, salary, available franking credits, company cash flow andhow the loans could progressively be reduced without simply allowing the samecycle to continue.
Tax planning shouldn't stop at 30June
A strategy that reduces taxable income today can still createobligations that need to be dealt with tomorrow.
In this case, the issue wasn't that Division 7A had been ignored.
The issue was that the strategy had been repeated withoutsufficient consideration of where the accumulated loans would eventually lead.
Good tax planning therefore asks more than:
“What does this save this year?”
It should also ask:
“Where does this leave the client five or seven years from now?”
Because sometimes the tax hasn't disappeared.
It's simply been deferred to another year.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. General informationonly. Division 7A outcomes depend on the particular payments, loans,agreements, repayments, timing and other circumstances involved.
The Salon Was Making Money — So Where Was the Rent?
Sometimes the numbers that are missing from a set of accounts canbe just as important as the numbers that are there.
We were reviewing the tax position of a sole trader operating asalon business. The business was generating revenue and had the usual expensesassociated with providing its services.
But one thing stood out.
There was no rent or other premises expense.
A salon has to operate somewhere.
So before simply preparing the tax return from the figuresprovided, we asked:
“Where are you actually operating the salon from?”
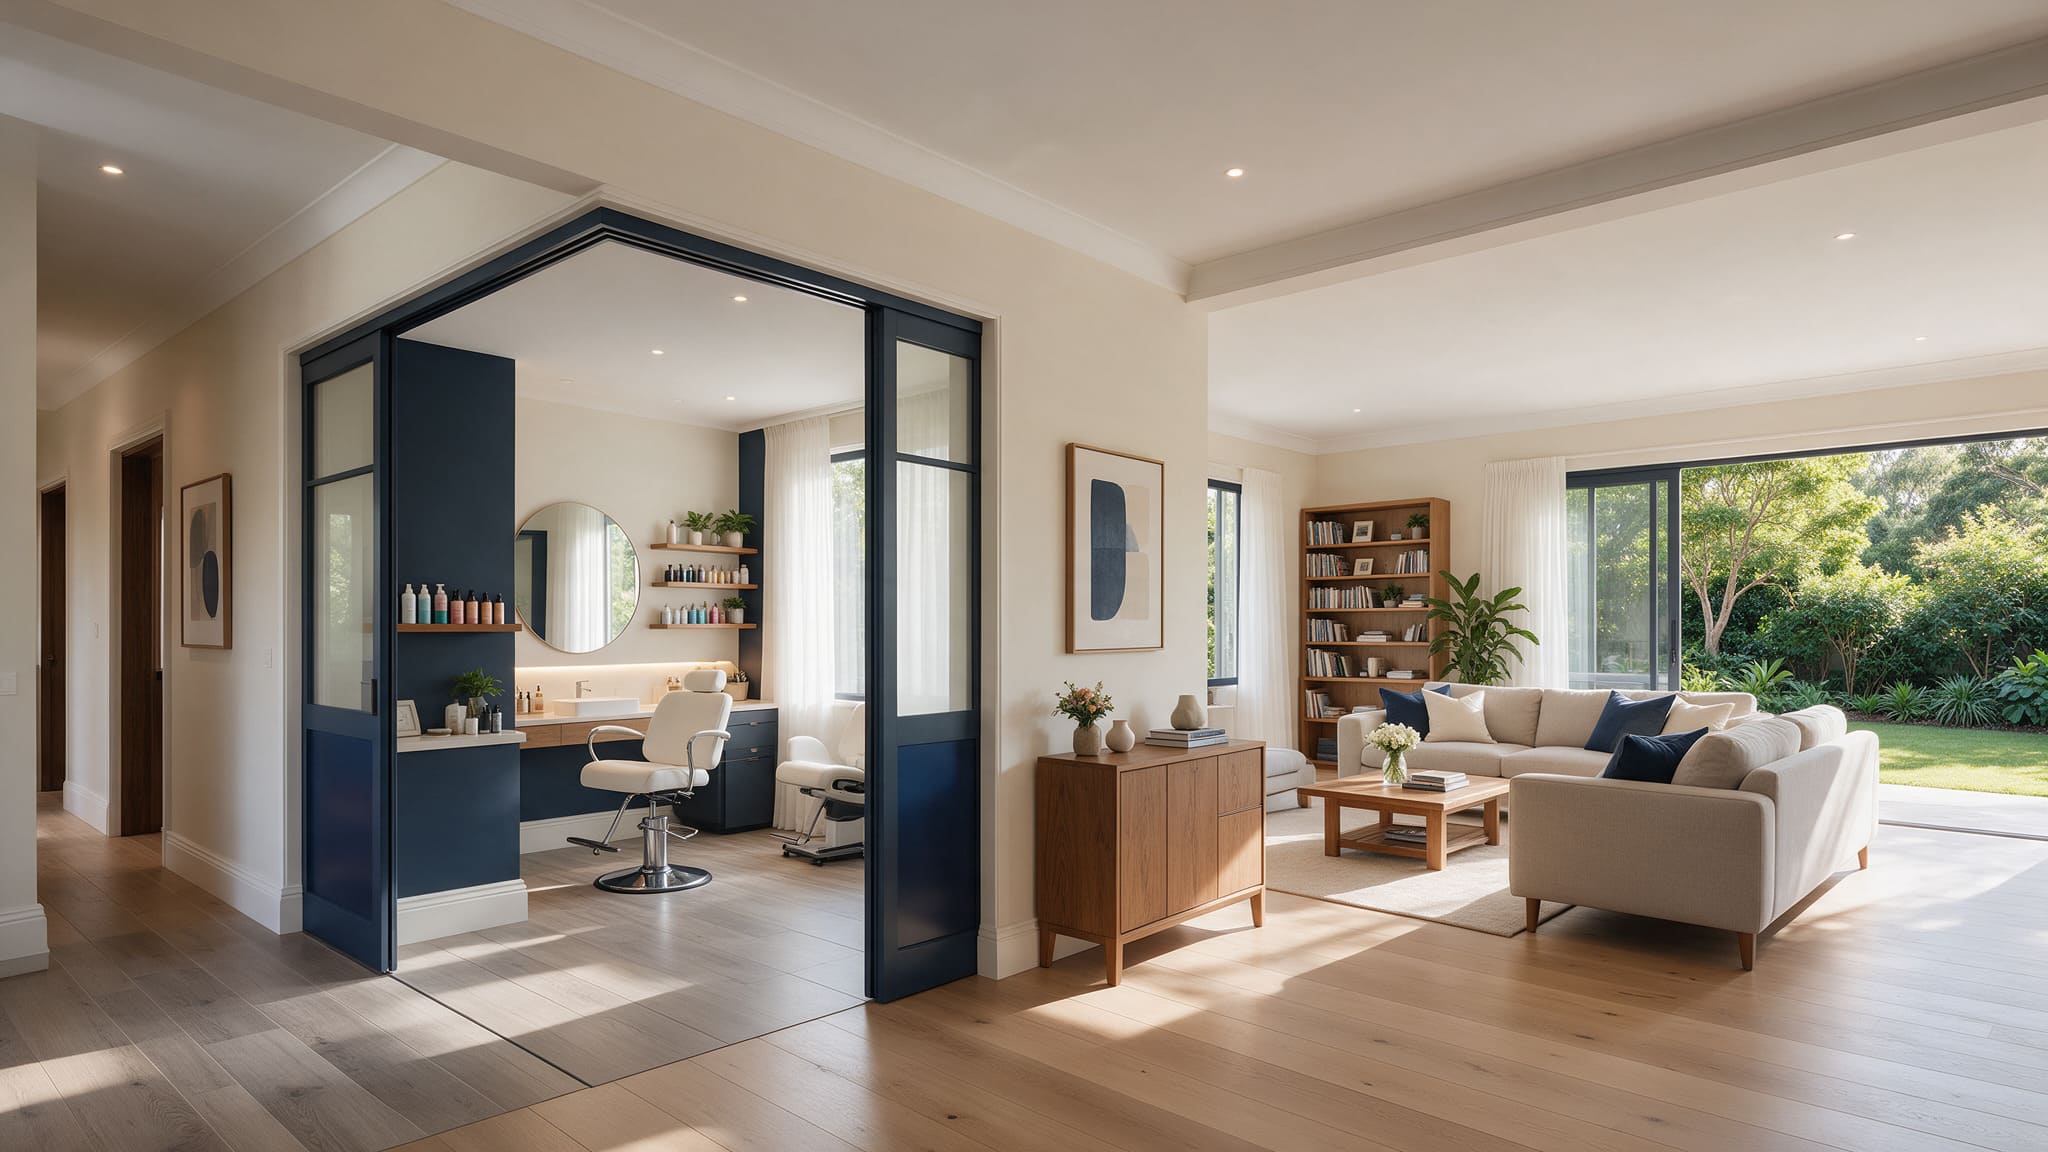
The business was operating from a dedicated room at home
The client explained that they were renting their home and had aseparate room set aside for operating the salon.
That changed the tax analysis.
For a sole trader operating a business from home, there is an important distinction between simply doing some administrative work from home and having part of the home that genuinely has the character of a place of business.
In this case, the separate room was being used for the salonbusiness.
That meant we needed to consider whether an appropriate proportion of the client's rent could be claimed as an occupancy expense, together with relevant running expenses associated with operating the business from the property.
The deduction wasn't automatically the entire rent. The businessand private use of the property needed to be appropriately separated, and theclaim supported by the client's circumstances and records.
Rent wasn't the only expense worth reviewing
Once we understood where the business was actually operating, the conversation went beyond rent.
We also considered whether an appropriatebusiness portion of other costs associated with operating the salon from therented home had been captured, such as electricity, cleaning and other relevanthousehold running expenses.
The objective wasn't to find expenses to claim simply because the client worked from home.
It was to establish what it genuinely cost to operate the salon from the property and make sure the deductible portion of those costs was properly considered.
Sometimes the missing number is the clue
If we had simply taken the bookkeeping at face value, the taxreturn could have been prepared using the expenses already recorded.
But the profit and loss statement told us something didn't quitemake commercial sense.
The business was operating a salon.
Where was the cost of the premises?
That simple question led us to understand how the businessactually operated and identify expenses that warranted further investigation.
Good tax review isn't only about checking whether the numbersprovided are correct.
Sometimes it's about recognising which number should logically be there — but isn't.
This case study has been generalised and certain details have been changed to protect client and business confidentiality. General informationonly. Home-based business deductions depend on the taxpayer's circumstances and the nature and use of the relevant area. Occupancy expenses such as rent aregenerally only available where the relevant part of the home has the characterof a place of business. Business and private expenses must be appropriatelyapportioned and substantiated. Different considerations can apply where the business is operated through a company or trust rather than by a sole trader.